Product review
Athene Performance Elite 7 Plus Annuity Review (2026)
Athene Performance Elite 7 Plus review: 0.95% Liquidity Rider, 5% bonus, return of premium after year 4, and matched illustrations vs the…
November 5, 2026
We are a direct-to-consumer, multi-carrier annuity platform. Compare guaranteed 5-year rates from 90+ top annuity companies side by side, download brochures, read company reviews and financial ratings, and apply online. Check each insurer's financial strength rating and the contract terms before you talk to anyone.
Rates vary by state, premium, and product availability. Guarantees depend on the issuing insurer's claims-paying ability.
The best 5-year fixed annuity rate is 7.15% from Knighthead Life on the Staysail 5 CA (Simple Interest), rated A- by AM Best.
A fixed annuity is a contract with a life insurance company. A multi-year guaranteed annuity (MYGA) credits a fixed interest rate for a set number of years. People often call it a "CD-type annuity" because the rate and term work in a similar way, but it is an insurance contract, not a bank CD, and it is not FDIC insured.
One leading option per guarantee period, 2 through 10 years. Each term links to its own rate page.
| Term | Carrier | Product | Guaranteed Rate | AM Best Rating | Apply |
|---|---|---|---|---|---|
| 2 years | CL Life | CL Sundance 2 | 5.25% | B++ | Apply |
| 3 years | Mountain LifeNot offered by MAS | Simple Summit 3 (Simple Interest) | 6.50%Simple interest | B- | Details |
| 4 years | Mountain LifeNot offered by MAS | Alpine Horizon 4 | 6.05% | B- | Details |
| 5 years | Knighthead Life | Staysail 5 CA (Simple Interest) | 7.15%Simple interest | A- | Apply |
| 6 years | Talcott Financial Group | EverStead MYGA 6 | 6.25% | A- | Apply |
| 7 years | Knighthead Life | Staysail 7 CA (Simple Interest) | 7.65%Simple interest | A- | Apply |
| 8 years | Talcott Financial Group | EverStead MYGA 8 | 6.30% | A- | Apply |
| 9 years | Talcott Financial Group | EverStead MYGA 9 | 6.30% | A- | Apply |
| 10 years | Revol One Financial | BreakThrough 10yr | 6.35% | B++ | Apply |
Source: AnnuityRateWatch feed, refreshed daily. AM Best ratings describe an insurer's financial strength, not a product's suitability for you. Contracts marked simple interest credit interest on the original premium only. Rates are subject to change without notice.
5-year comparison
The 15 highest guaranteed 5-year rates we track, with the details that matter when you compare them.
| Carrier / Product | Guaranteed Rate | AM Best Rating | Minimum Premium | Action |
|---|---|---|---|---|
| Knighthead LifeStaysail 5 CA (Simple Interest) | 7.15%Simple interest, about 6.30% compounded | A- | $100,000 | Get Quote |
| Mountain LifeNot offered by MASSimple Summit 5 (Simple Interest) | 7.00%Simple interest, about 6.19% compounded | B- | $5,000 | Details |
| Knighthead LifeStaysail 5 (Simple Interest) | 6.65%Simple interest, about 5.91% compounded | A- | $100,000 | Get Quote |
| IbexisMYGA Plus 5 (Simple Interest) | 6.60%Simple interest, about 5.87% compounded | A- | $100,000 | Get Quote |
| Knighthead LifeStaysail 5 CA With Liquidity | 6.55% | A- | $100,000 | Get Quote |
| Ability Insurance CompanyReliAbility MYGA 5 | 6.50% | B+ | $50,000 | Get Quote |
| IbexisMYGA Plus 5 (Simple Interest) CA | 6.50%Simple interest, about 5.79% compounded | A- | $100,000 | Get Quote |
| Mountain LifeNot offered by MASAlpine Horizon 5 | 6.45% | B- | $5,000 | Details |
| Wichita National Life Insurance CompanySecurity 5 | 6.40% | B+ | $10,000 | Get Quote |
| Revol One FinancialBreakThrough 5yr | 6.35% | B++ | $10,000 | Get Quote |
| Revol One FinancialDirectGrowth 5 | 6.35% | B++ | $10,000 | Get Quote |
| AspidaSynergy Choice 5 | 6.30% | A- | $100,000 | Get Quote |
| SBLI -Savings Bank Life Insurance of MAECAccumulate | 6.30% | A | $100,000 | Get Quote |
| CL LifeCL Sundance 5 | 6.25% | B++ | $20,000 | Get Quote |
| Farmers Life Insurance CompanyFarmers Safeguard Plus 5 | 6.25% | B++ | $10,000 | Get Quote |
Verified November 10, 2026. Minimum premiums are for non-qualified (after-tax) funds. Rates vary by state and premium. See every 5-year contract in the full fixed annuity rate table.
The highest rate isn't the only thing to compare. Look at the insurer's financial strength, how much you can withdraw each year without a surrender charge, and what happens when the 5-year guarantee ends.
A 5-year fixed annuity, also called a 5-year multi-year guaranteed annuity (MYGA), provides a guaranteed interest rate for a full five-year term. For a comparison across all term lengths, see our best fixed annuity rates page, or jump directly to 3-year MYGA rates or 7-year MYGA rates. Your money earns a fixed rate each year, and the insurance company guarantees that rate will not change during the 5 years.
5-year fixed annuities work similarly to certificates of deposit (CDs), but they are issued by an insurance company, not a bank.
My Annuity Store does not charge you a fee. Most MYGAs have no annual fees, but withdrawing more than the free withdrawal amount before the term ends can trigger a surrender charge.
It is important to note that there is a 30-day window at the end of an annuity contract in which you will need to make a decision. If you do nothing, your annuity will renew for another term at whatever annuity rate is being offered at that time. You will have several options at the end of your annuity contract, and we’ve listed them below.
You should be aware of possible tax implications. Tax considerations and potential ramifications will vary based on your annuity contract and situation. My Annuity Store recommends you carefully assess your options and consult an annuity specialist to align your decision with your financial objectives.
5 year fixed annuity rates can vary based on several factors, including:
For the most accurate and relevant 5-year fixed annuity (MYGA) rates for your situation:
If you’d like help comparing options or confirming your exact rate before you apply, call us at 855-277-8088 or request a personalized quote.
When shopping for the best fixed annuity rate, it is important to look past the highest rate and consider all features of each annuity.
Key Features to Consider:
Simple vs Compound Interest
When evaluating the best 5 year fixed annuity rates, you will likely see that the majority of MYGAs, or multi-year guarantee annuities, offered by insurance companies use compound interest. Knighthead Life’s Staysail MYGA takes a more straightforward approach with simple interest.
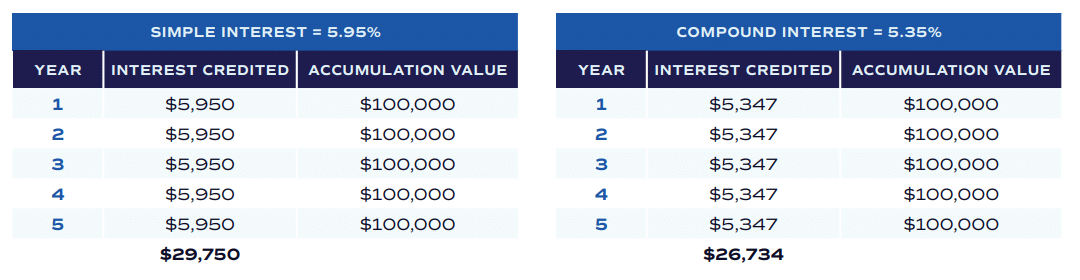
Let’s compare two five-year fixed annuities with an initial deposit of $100,000.
The simple interest MYGA pays a rate of 5.95%, and compound interest MYGA pays a crediting rate of 5.35% annually. As you can see from the table of values below, both individuals have the same accumulated value after five years, making the products rate-equivalent.
The Difference: Income
What if you’d like to use your MYGA for income purposes and take interest-only withdrawals annually to cover certain living expenses? See how the compound and simple interest MYGAs compare over five years of annual, interest-only withdrawals. Use our simple vs. compound interest calculator
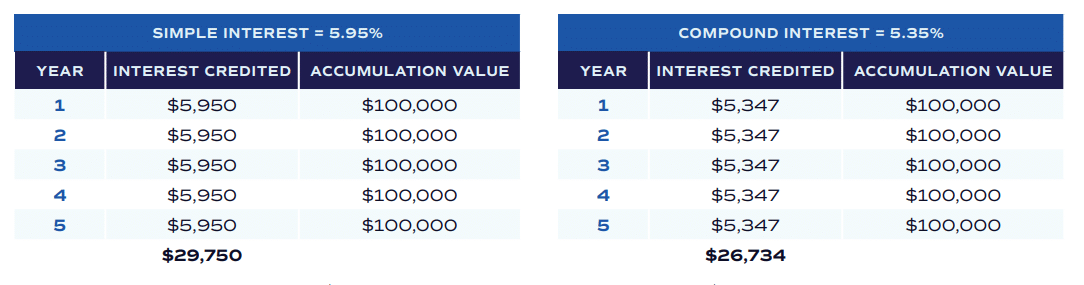
The simple interest option generates $29,750 versus the compound interest total of $26,734. That’s 11.5% more income. When it comes to income, the simple interest MYGA provides more value.
Many 5 year fixed annuities allow you to withdraw the interest earned, or up to 10% of your account value annually, without penalty. While some fixed annuities have no free withdrawal options. Example: If you have $100,000 in your annuity, you could withdraw up to $10,000 in year two without facing surrender charges.
If you do not want or need any free withdrawal options, it may be wise to consider annuities with no free withdrawal provisions because they typically pay a higher guaranteed rate.
A surrender charge is a fee applied by an insurance company4 when you withdraw money from an annuity during the “surrender period,” which is during the 5 year annuity contract.
Surrender charges are applied as a percentage of your annuity’s account value and decrease over time.
They reduce the total cash value you receive and are typically highest at the start, often becoming zero after 7-8 years, with some contracts allowing small penalty-free withdrawals annually.
Fixed annuities, bonds, and CDs are all worth considering if you are looking for a safe and steady way to grow your retirement savings. They each offer predictable returns and safety of principal, but there are differences among them.
The table below compares and contrasts the differences.
| Feature | 5 Year Fixed Annuity | 5 Year Bank CD |
|---|---|---|
| Current Rates | 5.50% – 6.30% | 3.50% – 4.50% |
| Tax Treatment | Tax-deferred growth | Taxed annually on interest |
| FDIC/State Protection | State guaranty association* | FDIC insured up to $250K |
| Early Withdrawal | Surrender charges apply** | Penalty (typically 3-6 months interest) |
| Best For | Long-term savers, retirement funds | Emergency funds, short-term goals |
Fixed Annuity Advantages:
Tell us a little about your plans. A licensed annuity specialist will follow up with rates that fit your state, amount, and term. No obligation.
Request received
Thanks. A licensed annuity specialist will contact you about 5-year options for your state within one business day. Check your inbox for confirmation.
Product reviews and rate news from our team.
Athene Performance Elite 7 Plus review: 0.95% Liquidity Rider, 5% bonus, return of premium after year 4, and matched illustrations vs the…
Nasdaq FC Index (BOFANFCC): how this fixed index annuity index works, performance, and which carriers offer it at My Annuity Store.
Bloomberg US Dynamic Balance Index II: how this fixed index annuity index works, performance, and which carriers offer it at My Annuity…
The 10-year Treasury yield fell from 5.29% to 4.94% in October, the biggest monthly drop in Treasury yields since 2024. Carriers reprice…
Regulators are drafting standardized index scenarios for FIA illustrations. Here is what changed, what has not, and how to read the illustration…
The Fed raised rates to 3.75-4.00% on Sept. 16, 2026. What the Fed rate hike means for annuity rates, product by product,…
These are the top 10 insurers by fixed-rate deferred annuity sales in 2025, according to LIMRA. U.S. fixed-rate deferred annuity sales reached $165.3 billion for the year, and the top 20 carriers wrote 75% of it.
Sales volume shows which companies sell the most. It does not measure financial strength or tell you whether a product suits you. Check the AM Best rating and read the best fixed annuity companies guide before you choose.
| Rank | Company | 2025 fixed-rate deferred sales |
|---|---|---|
| 1 | Athene Annuity & Life | $17.55 billion |
| 2 | New York Life | $16.97 billion |
| 3 | Massachusetts Mutual Life | $12.21 billion |
| 4 | Corebridge Financial | $10.49 billion |
| 5 | USAA Life | $7.63 billion |
| 6 | Nationwide | $7.18 billion |
| 7 | Pacific Life | $5.42 billion |
| 8 | Western Southern Group | $5.41 billion |
| 9 | American National Insurance | $5.15 billion |
| 10 | Symetra Financial | $5.09 billion |
Source: LIMRA, U.S. Individual Fixed Annuity Sales Breakout, 2025 Year-End Rankings (U.S. Individual Annuities Sales Survey). Fixed-rate deferred column only. Company names as LIMRA reports them; each links to our review of that carrier.
When you compare 5-year fixed annuity rates, weigh the insurer's rating and the withdrawal terms alongside the rate itself.
It takes three steps. First, compare guaranteed rates, terms and insurer ratings on this page, or request a quote. Second, talk with a licensed annuity specialist about your goals, your state's availability and the contract terms, with no obligation. Third, if you choose a product, we help you complete the insurer's annuity application and fund the contract.
The insurance company pays us a commission after a contract is issued. It is built into the product's pricing rather than deducted from your premium, so the rate you see is the rate the carrier credits. Our process explains every step.
No. We never sell your information. We use what you send us to prepare your quote and follow up, as described in our privacy policy.
No. You pay no fees and no commissions to us. Annuity contracts can carry their own costs: surrender charges for early withdrawals, possible market value adjustments, and charges for optional riders. Each contract's disclosure lists them.
No. Annuities are issued by insurance companies, not banks, and are not FDIC insured. Guarantees depend on the issuing insurer's financial strength and claims-paying ability. Your state guaranty association provides limited protection if an insurer fails, and limits vary by state.
Usually a multi-year guaranteed annuity (MYGA) that credits one fixed rate for 5 years, with a surrender schedule over the same period. At the end of the term you can typically renew, move the money through a 1035 exchange, annuitize, or withdraw. Our guide to what happens when an annuity matures walks through each option.
The best 5-year fixed annuity rate is 7.15% from Knighthead Life on the Staysail 5 CA (Simple Interest), rated A- by AM Best. As of November 10, 2026, the highest guaranteed fixed annuity rate we track is 7.65% for a 7-year MYGA from Knighthead Life (simple interest). Rates vary by state, premium and availability, so compare the full fixed annuity rate table before you apply.
How surrender periods work and what you can take out each year without a penalty.
Your renewal, rollover, income and withdrawal options at the end of the guarantee period.
Move an existing annuity into a new contract without triggering a taxable event.

Written by
Jason founded My Annuity Store in 2020 to help people compare annuities from many insurers and buy with full information. He brings more than 20 years of annuity industry experience and works with clients on MYGAs, income annuities, and fixed index annuities.
You’re in. Here’s your guide.
Your download should start automatically. If it doesn’t, use the button below. We’ve also added you to our newsletter for rate updates and new guides.
Download the Guide (PDF) ↓