What Is the Athene Performance Elite 10?
The Athene Performance Elite 10 is a fixed index annuity with a 10-year surrender period, a premium bonus credited on day one, and no annual fees on the base contract. The 20% bonus on our illustration (it varies by state and issue age) is paid for with crediting rates about 59% of the no-bonus Athene Performance Elite 7‘s (see the official Athene Performance Elite brochure).
This review uses Athene’s full rate sheet and a live illustration we ran on October 9, 2026 for a 60-year-old male with a $100,000 non-qualified premium.
Product Overview
| Feature | Details |
|---|---|
| Carrier | Athene Annuity and Life Company (AM Best A+, S&P A+, Fitch A+, Moody’s A1) |
| Product Type | Fixed Index Annuity (FIA), single premium, bonus |
| Premium Bonus | 20% on our illustration; varies by state and issue age |
| Bonus Vesting | 0% in year 1, then 10% per year; fully vested after year 10. Never forfeited at death |
| Surrender Schedule | 8.3% / 8% / 7.1% / 6.2% / 5.3% / 4.4% / 3.5% / 2.6% / 1.6% / 0.9%, then 0% (varies by state) |
| Market Value Adjustment | Yes, on excess withdrawals and surrenders during the surrender period (how an MVA works) |
| Premium | $10,000 minimum ($5,000 in some states); $2,000,000 maximum |
| Issue Ages | 0 to 78 (owner and annuitant) |
| Free Withdrawal | None in year 1; 5% of accumulated value per year from year 2 (not cumulative) |
| RMD-Friendly | Yes, RMDs are penalty-free from year 1 |
| Waivers | Confinement (60+ days, after year 1) and terminal illness (after year 1): up to 100% with no surrender charge or MVA |
| Death Benefit | Greater of accumulated value (including the full bonus) or Minimum Guaranteed Contract Value |
| Guaranteed Minimum Value | 87.5% of premium (bonus excluded), growing at 1.9% per year |
| Income Rider | None |
| Optional Liquidity Rider | Performance Elite 10 Plus, 0.95% per year |
| Availability | Most states (not New York) |
Index Crediting Strategies and Current Rates
The Performance Elite 10 offers the same seven indices as the Performance Elite 7, in fee-based and no-fee versions. Fee-based options charge 1.25% annually but offer significantly higher participation rates. All strategies are point-to-point with a participation rate, except the S&P 500, which uses a cap.
1-Year Reset Strategies (Current as of October 2026)
| Index | No Fee | With 1.25% Fee | Backtested (No Fee) |
|---|---|---|---|
| AI Powered Global Opportunities | 95% | 135% | 10.49% |
| Nasdaq FC | 77% | 110% | 7.61% |
| UBS Innovative Balanced | 95% | 135% | 7.39% |
| S&P 500 FC (0.50% decrement) | 60% | 85% | 7.13% |
| BNP Paribas Multi-Asset Diversified 5 | 130% | 185% | 5.85% |
| S&P 500 (cap) | 5.5% | 8% | 4.38% |
| AI Powered US Equity | 107% | 150% | 4.06% |
2-Year Reset Strategies (Current as of October 2026)
| Index | No Fee | With 1.25% Fee | Backtested (No Fee) |
|---|---|---|---|
| AI Powered Global Opportunities | 125% | 180% | 13.47% |
| Nasdaq FC | 120% | 170% | 9.09% |
| UBS Innovative Balanced | 125% | 180% | 8.50% |
| S&P 500 FC (0.50% decrement) | 80% | 115% | 8.04% |
| BNP Paribas Multi-Asset Diversified 5 | 180% | 255% | 6.29% |
| AI Powered US Equity | 140% | 195% | 4.71% |
Athene rate sheet via Annuities Genius, October 9, 2026 (age 60, $100,000 non-qualified). Backtested = annualized average credited rate over the last 10 calendar years at today’s rates, excluding the bonus; hypothetical, not a projection. Rates vary by state and change at each index term.
What stands out:
- 1-year fixed account: 2.9% (0.25% minimum on renewal), versus 4.85% on the Performance Elite 7.
- S&P 500 5.5% cap: the only plain-vanilla index, and low for a 10-year FIA. The Performance Elite 7 offers 9.75%.
- The fee matters more here: 1-year Nasdaq FC jumps from 77% to 110% with the fee (backtest 7.61% to 10.71%, about 9.46% net).
- Best no-fee options: 2-year Nasdaq FC at 120% (9.09% backtest; index live since January 29, 2020) and 2-year AI Powered Global Opportunities.
- AI Powered Global Opportunities: highest backtest, but it deducts a 0.85% annual cost inside the index and was added to Athene’s lineup only in August 2023 (announcement), so most of its backtest is simulated. Our illustration software would not illustrate it.
- BNP Paribas MAD 5: 5% volatility target, 0.50% annual fee built in (BNP Paribas), live since January 26, 2016. At 130% it backtested only 5.85%.
- Weakest option: AI Powered US Equity, 107% participation for a 4.06% backtest.
- Proprietary-heavy menu: six of the seven indices are proprietary or volatility-controlled.
Compare current fixed index annuity rates across carriers on our FIA rate table.
Hypothetical Historical Rate of Return
Illustration: $100,000 plus the 20% bonus ($120,000 accumulated value), 50% 1-year Nasdaq FC (77%) and 50% 1-year BNP Paribas (130%), no fee, today’s rates applied to 2016 through 2025.
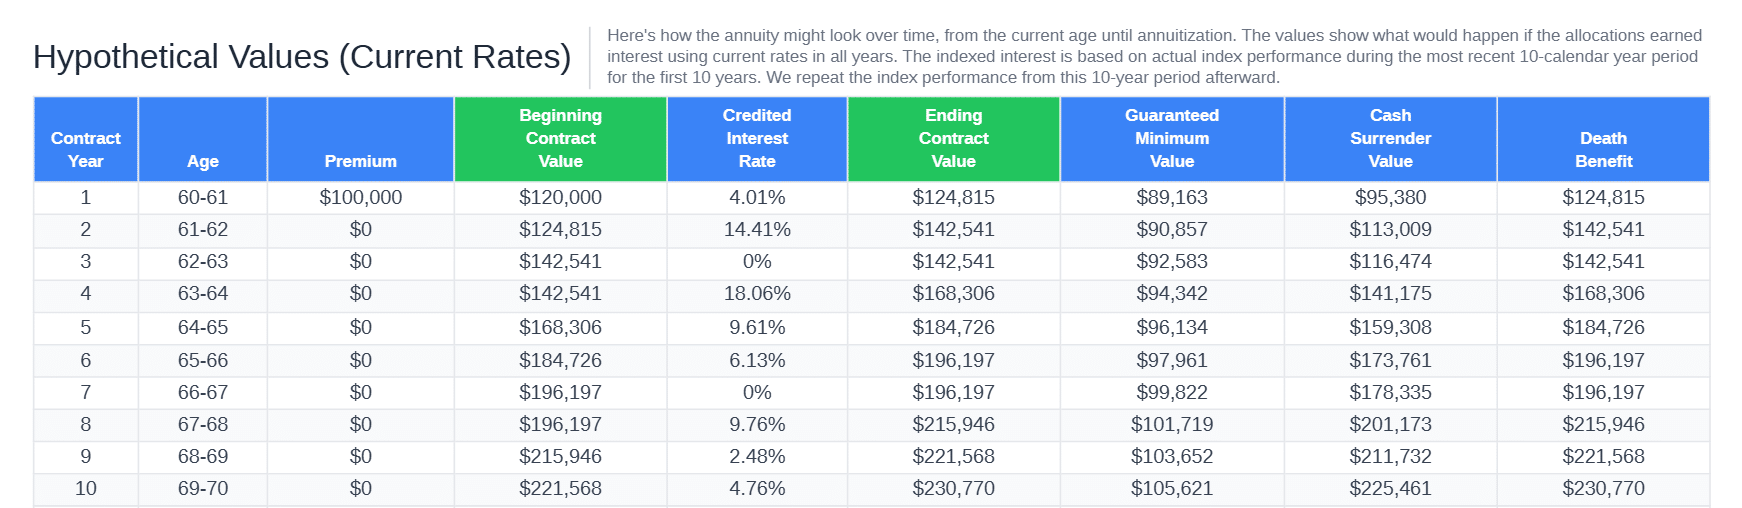
| Year | Accumulated Value | Cash Surrender Value | Annualized (Cash Value) |
|---|---|---|---|
| 1 | $124,815 | $95,380 | n/a |
| 7 | $196,197 | $178,335 | 8.6% |
| 10 | $230,770 | $225,461 | 8.5% |
- Year 1 gap: $124,815 of accumulated value but $95,380 of cash value, because the bonus is 0% vested in year 1.
- Zero years held flat: 0% credits in 2018 and 2022, with no loss either time (the 0% floor).
- Backtest caveat: Nasdaq FC did not exist before 2020, so four of these 10 years are simulated for that half.
- Most defensible number: BNP Paribas’s low period (2015-2024), almost all live data, credited 4.90% a year at the Performance Elite 10’s 130% rate.
- Ignore the lifetime figure: the illustration’s 6.73% “annual effective rate” to age 95 repeats the 2016-2025 decade.
- Our planning range: 3% to 5% a year in credits, plus roughly 1.8 points a year from the bonus over 10 years.
- MYGA benchmark: At today's top 10-year rate of 6.35% (compound), $100,000 grows to about $185,087 over 10 years, a gain of $85,087. See current MYGA rates.
Guaranteed Values (If the Index Pays 0% Every Year)
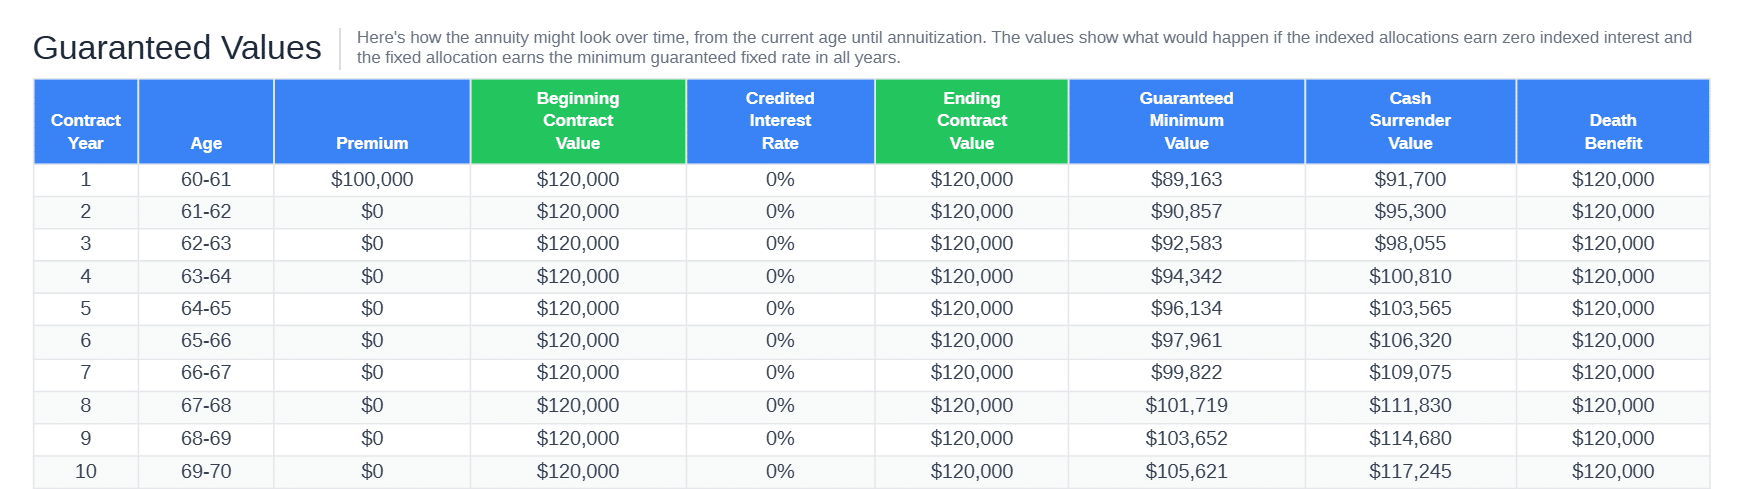
- Accumulated value stays at $120,000, and the death benefit is $120,000 from day one.
- Cash surrender value: $91,700 in year 1, passes $100,000 in year 4 ($100,810), and reaches $117,245 in year 10.
- That is about $11,600 more than the Performance Elite 7’s guaranteed year-10 value ($105,621). This floor is the 10’s strongest feature.
Performance Elite 10 vs Performance Elite 7
Same day, same client, same 50/50 allocation on both products:
| Performance Elite 10 | Performance Elite 7 | |
|---|---|---|
| Premium bonus | 20% | None |
| Surrender period | 10 years | 7 years |
| 1-year Nasdaq FC / BNP Paribas | 77% / 130% | 130% / 220% |
| S&P 500 cap / fixed account | 5.5% / 2.9% | 9.75% / 4.85% |
| Free withdrawal | 5% from year 2 | 10% from year 1 |
| Maximum issue age | 78 | 83 |
| Illustrated cash value, year 10 | $225,461 | $290,221 |
| Guaranteed cash value, year 10 | $117,245 | $105,621 |
- Break-even: about 4.6% a year. If the 7’s strategies average more than that over 10 years, the 7 wins; below it, the 10’s bonus wins.
- At 4% a year the 10 comes out slightly ahead; at 6% the 7 leads by roughly 9% of premium.
- Assumes today’s rate ratio holds at every renewal, which Athene does not guarantee.
Pros and Cons
Pros
- 20% premium bonus credited on day one
- Stronger guaranteed floor: cash value passes premium in year 4 even with zero credits
- Bonus-inclusive death benefit from day one, with no vesting adjustment at death
- No annual fees on the base contract. The 1.25% fee only applies if you choose fee-based crediting strategies
- Strong carrier backing. Athene holds an A+ rating from AM Best
Cons
- Crediting rates about 59% of the Performance Elite 7’s, including a 5.5% S&P 500 cap and 2.9% fixed account
- 10-year surrender period plus an MVA
- Tight liquidity: nothing free in year 1, then 5% a year; excess withdrawals also forfeit unvested bonus
- Proprietary-index heavy, with backtests that rest partly on simulated history
- No lifetime income rider
Bottom Line Verdict
Best for conservative buyers who expect modest returns, or who value the guaranteed floor and bonus-inclusive death benefit, and won’t need more than 5% a year for 10 years. Growth-focused buyers should start with the Performance Elite 7. Request matched illustrations on both for your age and state.
Frequently Asked Questions
What is the Athene Performance Elite 10 premium bonus?
20% on our illustration, credited on day one; the exact bonus varies by state and issue age. It vests 10% a year and is fully vested after year 10.
What is the minimum investment for the Athene Performance Elite 10?
$10,000 ($5,000 in some states), single premium only. The maximum is $2,000,000 without home office approval.
What is the maximum issue age?
78 for both the owner and the annuitant.
What is the Athene Performance Elite 10 surrender schedule?
8.3%, 8%, 7.1%, 6.2%, 5.3%, 4.4%, 3.5%, 2.6%, 1.6%, and 0.9% in years 1 through 10 on our illustration; schedules vary by state. An MVA also applies.
What happens to the bonus if I surrender early?
You forfeit the unvested portion, plus the surrender charge and MVA. The bonus is never forfeited at death, and free withdrawals and RMDs don’t trigger the vesting adjustment.
Is the Performance Elite 10 better than the Performance Elite 7?
Only if returns stay low. In our matched illustrations the Performance Elite 7 finished about $65,000 ahead at year 10; the 10 wins when credits average under about 4.6% a year.
Can I add an income rider to the Performance Elite 10?
No. Athene products like the Athene Agility 10 pair better with income riders.
What is the Performance Elite 10 Plus?
The same contract with a Liquidity Rider for 0.95% a year: 10% free from year 1 (20% if nothing was withdrawn the prior year), return of premium after year 4, and penalty-free annuitization after year 7. See our Athene Performance Elite 10 Plus review.
Is Athene a good annuity company?
Athene is rated A+ by AM Best, S&P, and Fitch, and A1 by Moody’s. See our Athene company review.
Other Athene Reviews
Sources: Athene Performance Elite brochure (04/22/26); Athene rate sheet and illustration via Annuities Genius, October 9, 2026; Athene index announcement (August 2023); BNP Paribas; NAIC Consumer Information Source.
This review is for educational purposes only and is not a recommendation or an offer to sell any annuity. Product features, index options, and rates can and do vary by state, and this product is not available for sale in every state. Always request a carrier illustration and work with a licensed annuity agent before you buy.