
Is the Corebridge Power 7 Protector a Good Annuity?
The Corebridge Power 7 Protector is a 7-year fixed index annuity issued by American General Life, a Corebridge company, designed for safe accumulation. If you want a deeper index menu over 10 years, see our Corebridge Power Select Builder review. The verdict: a 9.6% S&P 500 cap with no fee, but four menu options charge 1.5% a year.
- Best for: savers in their 60s or 70s moving CD or MYGA money who want S&P 500 upside and can hold 7 years.
- Not for: anyone who wants guaranteed lifetime income, or who may need more than 10% a year before year 8.
Corebridge Power 7 Protector at a Glance
| Feature | Details |
|---|---|
| Purpose | Safe accumulation (no bonus, no income rider) |
| Carrier | American General Life, a Corebridge Financial company (AM Best A, S&P A+, Fitch A+, Moody’s A2) |
| Surrender schedule | 7 years: 8%, 7%, 6%, 5%, 4%, 3%, 2% |
| Market value adjustment | Yes, on excess withdrawals during the surrender period (how an MVA works) |
| Premium | $25,000 minimum, $2,000,000 maximum without approval; added premium only in the first 30 days |
| Issue ages | 18 to 85 |
| Free withdrawal | 10% of prior-anniversary contract value a year, not cumulative |
| Waivers | Nursing home, terminal illness, and extended care (extended care ends at age 86) |
| Death benefit | Greater of contract value or minimum withdrawal value |
| Guaranteed minimum value | 87.5% of premium growing at 2.9% (90% in NJ) |
| Bonus and rider | None; optional 1.5% fee only on four Enhanced accounts |
| Illustration basis | July 20, 2026; male 69; Arizona; $100,000 non-qualified; 50/50 S&P 500 par and cap |
What Does the Corebridge Power 7 Protector Pay?
| Strategy | No-fee rate | Enhanced rate (1.5% fee) |
|---|---|---|
| S&P 500 1-year cap | 9.6% cap | – |
| S&P 500 1-year participation | 52% | 62% |
| S&P 500 1-year trigger | 7% | – |
| ML Strategic Balanced 1-year / 2-year | 110% / 140% | 140% / 190% |
| AQR DynamiQ 1-year / 2-year | 165% / 240% | 235% / 315% |
| PIMCO Global Optima 1-year / 2-year | 70% / 100% | 95% / 135% |
| 1-year fixed account | 4.00% | – |
Rates as of July 2026; they can change each contract anniversary.
- The two S&P 500 accounts are the reason to buy: a 9.6% cap or 52% uncapped participation, with no fee.
- Big participation rates, small indexes: AQR DynamiQ at 235% to 315% backtests at only 5.41% to 7.60% a year.
- A real fixed account: 4.00% for year one, not the token 1% to 2% many FIAs pay.
- Benchmark it: compare these against current fixed index annuity rates from other carriers.
Hypothetical Historical Rate of Return
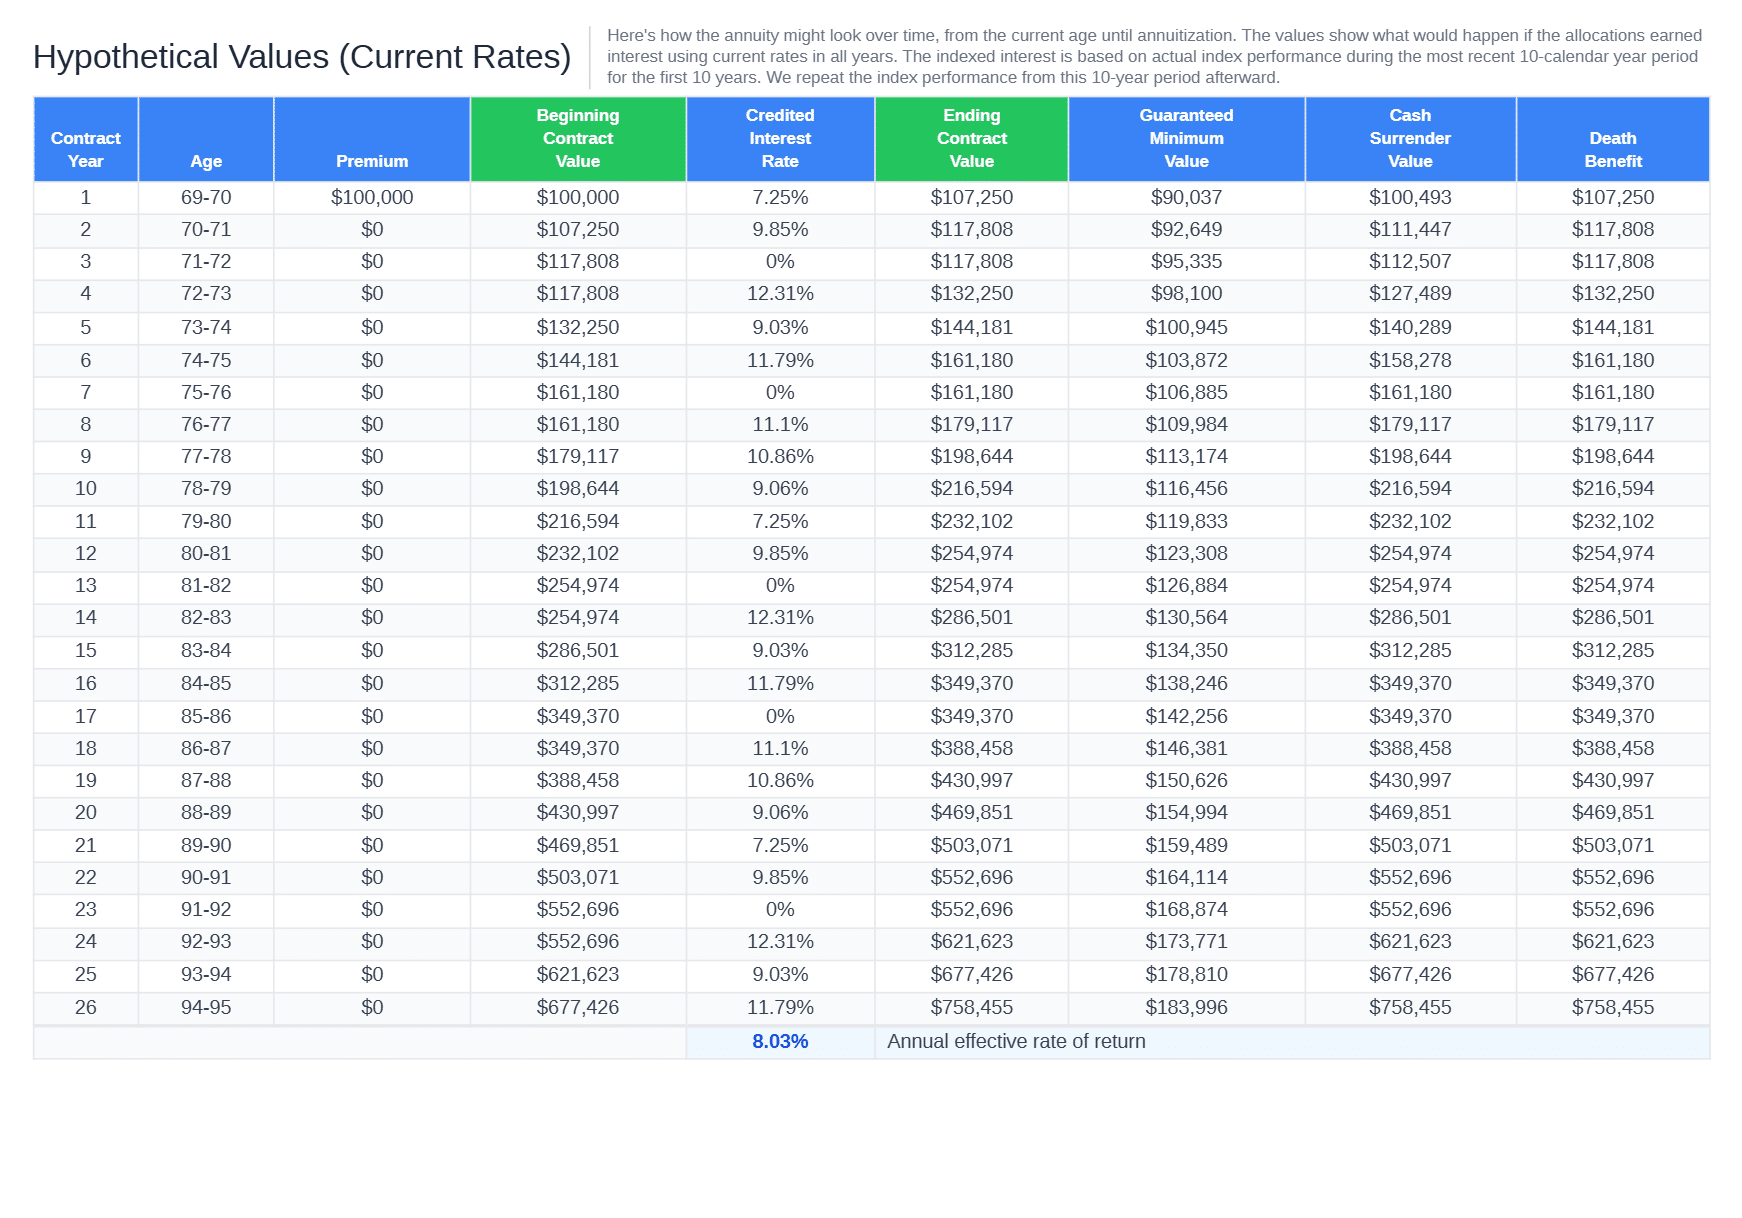
Our illustration split $100,000 evenly between the S&P 500 52% participation and 9.6% cap accounts.
| Scenario | Annual rate | Value after 10 years |
|---|---|---|
| Most recent 10 years, 50/50 blend | 8.03% | $216,594 |
| Worst window (from 2007), participation account | 5.28% | – |
| Worst window (from 2007), cap account | 6.02% | – |
| Index pays 0% every year | 0% | $100,000 contract value; $116,456 minimum withdrawal value |
- Backtest caveat: the 8.03% window held one of the strongest stock runs on record, with only two zero years.
- Our planning range: plan on 4% to 7% a year. The worst window still landed near 5% to 6%.
- Early exit cost: the year-one cash surrender value was $93,700 on $100,000.
- MYGA benchmark: At today's top 7-year rate of 7.10% (simple interest), $100,000 grows to about $149,700 over 7 years, a gain of $49,700. See current MYGA rates.
Hypothetical vs. guaranteed
Use our fixed annuity calculator to compare this hypothetical value to the guaranteed growth you would earn in a fixed annuity.
Get your Power 7 Protector illustration for your age and state
Send us your premium amount, your state, and when you need the money. We will come back with current numbers on this contract and comparable ones from the 90+ top annuity companies on our platform, in writing.
Corebridge Power 7 Protector Strengths and Red Flags
What it does well
- 9.6% no-fee S&P 500 cap: at the competitive end for 7-year FIAs in July 2026.
- Short, gentle schedule: 7 years ending at 2%, with free withdrawals based on contract value, not premium.
- No bonus to claw back: the budget goes into the cap and the 4% fixed account instead.
Red flags
- 1.5% Enhanced account fee: charged even in 0% years, so a flat year on those accounts loses 1.5%.
- Expensive early exit: an 87.5% floor, an 8% year-one charge and an MVA.
- Filler menu: ten of the 16 strategies backtest below 7%.
- Limited waivers: free withdrawals don’t carry over, and the extended care waiver ends at 86.
Final verdict: the Corebridge Power 7 Protector is built for safe accumulation with a short 7-year commitment. It earns our 4.0 rating for savers who use the no-fee S&P 500 accounts. For 10 years and more index choices, the Corebridge Power Select Builder beats the Corebridge Power 7 Protector.
Compare live rates on 137 fixed index annuities or visit our annuity review database.
This review is for educational purposes only and is not a recommendation or an offer to sell any annuity. Product features, index options, and rates can and do vary by state, and this product is not available for sale in every state. Always request a carrier illustration and work with a licensed annuity agent before you buy.
Frequently Asked Questions
Does the Corebridge Power 7 Protector have an income rider?
No. It is a pure accumulation annuity. Corebridge sells a separate version with an income rider, the Power 7 Protector Plus Income, at lower crediting rates.
Can I lose money in the Power 7 Protector?
Not from the index on the no-fee accounts. You can lose value from the 1.5% fee on Enhanced accounts, surrender charges of 8% down to 2%, and the MVA during the first 7 years.
What is the minimum guaranteed value?
It starts at 87.5% of premium and currently grows at 2.9% a year. On $100,000 it passes the original premium in year 5 and reaches $116,456 by year 10.
Is the Power 7 Protector available in New York?
No. It is also unavailable in Idaho, Guam, Puerto Rico and the U.S. Virgin Islands. It is sold in the other 45 states and Washington, D.C.



