
Is the Allianz 222+ a Good Annuity?
The Allianz 222+ (Allianz 222) is a 10-year fixed index annuity issued by Allianz Life, designed for lifetime income that can grow with index credits. If your goal is the highest guaranteed income, see our Athene Ascent Pro 10 Bonus review; for safe growth, the Allianz Accumulation Advantage+. The verdict: no rider fee and a 45% income bonus, but only $7,975 a year guaranteed at 70.
- Best for: buyers 55 to 65 who can wait 10 years for income and already cover basic bills with Social Security or a pension.
- Not for: anyone who wants a locked-in income number on day one, or who may need income before contract year 11.
Allianz 222+ at a Glance
| Feature | Details |
|---|---|
| Purpose | Lifetime income that can grow with index credits |
| Carrier | Allianz Life Insurance Company of North America (AM Best A+, S&P AA, Moody’s Aa3) |
| Surrender schedule | 10 years: 9.3%, 9.3%, 8.3%, 7.3%, 6.25%, 5.25%, 4.2%, 3.15%, 2.1%, 1.05% |
| Market value adjustment | Yes, on withdrawals above the free amount (how an MVA works) |
| Premium | $20,000 minimum, $2,000,000 maximum without home office approval; add premium for 18 months |
| Issue ages | 0 to 80 |
| Free withdrawal | 10% of premium or beginning-of-year value, whichever is greater; unused amounts carry over up to 20% |
| Death benefit | Lump sum of accumulation value (or guaranteed minimum, if greater), or the income value paid over at least 5 years |
| Guaranteed minimum value | $90,700 cash value in year 1, $105,621 in year 10 on $100,000 |
| Bonus | 45% premium bonus to the Protected Income Value (income value only) on premium paid in the first 18 months |
| Income rider | Built-in Protected Income Value, no fee; lifetime income after 10 contract years |
| Index options | 18 strategies on 1-, 2- and 5-year terms, plus a 3.2% fixed account; allocation charge 0% today, 2.5% maximum |
| Illustration basis | October 14, 2026; male, 60, Arizona; $100,000 non-qualified |
Full details are in the official Allianz 222+ brochure[4]. Compare its index rates with today’s fixed index annuity rates.
How Much Income Does the Allianz 222+ Pay?
| Rider feature | Details |
|---|---|
| Rider fee | None |
| Income value at issue | $145,000 ($100,000 premium plus the 45% bonus) |
| Roll-up | 150% of any interest credited; nothing in a 0% year (no guaranteed roll-up) |
| Wait period | 10 contract years |
| Payout rate | 5.00% to 6.00% by age band; 5.5% at age 70 |
| Guaranteed income at 70 | $7,975 a year for life |
| Hypothetical income at 70 | $25,872 a year, rising after any credited year |
| Allianz Income Multiplier | Doubles income to $15,950 if you cannot do 2 of 6 daily activities, or after 90 days of care confinement |
- When the rider beats plain withdrawals: at $7,975 a year, the guaranteed account value runs out around age 82. Every check after that is Allianz’s money.
- Waiting adds little on the guarantee: with zero credits the income value stays at $145,000. Only the payout rate steps up, from 5% at 69 to 5.5% at 70.
- Income keeps growing: after payments start, each credited year raises the check by 150% of the interest rate.
- Your own numbers: try our income rider calculator for your age, premium and start date.
How Much Guaranteed Lifetime Income Can You Buy?
Live quotes from today’s carrier feedSee what the Allianz 222+ would pay you for life before the October 28 Fed decision
Lifetime income depends on your age, your premium and when you start. Run the numbers in our income rider calculator, or request a quote with current carrier figures for your age and state, in writing.
Hypothetical Historical Rate of Return
Our October 14, 2026 illustration put 100% in the 1-year S&P 500 Futures ER point-to-point strategy at a 55% participation rate. It applies today’s rates to 2016 through 2025.
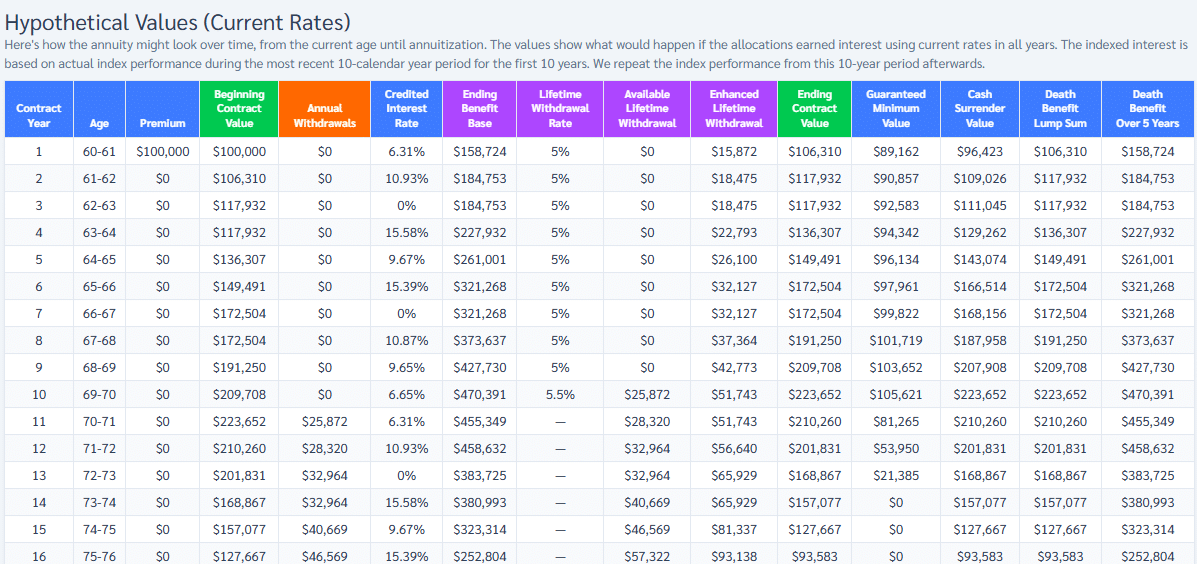
| Year | Hypothetical value | Cash surrender value | Guaranteed cash value | Hypothetical income value |
|---|---|---|---|---|
| 1 | $106,310 | $96,423 | $90,700 | $158,724 |
| 10 | $223,652 | $223,652 | $105,621 | $470,391 |
- Backtest caveat: 8.38% a year came from a strong decade, and the low period (2014 to 2023) still showed 7.5%. Allianz can change the 55% rate every year.
- The income gap is the whole bet: $25,872 hypothetical against $7,975 guaranteed. Two of the ten years credited 0% and added nothing.
- Our planning range is 4% to 7% a year in credits, which lands income well between those two numbers.
- MYGA benchmark: At today's top 10-year rate of 6.30% (compound), $100,000 grows to about $184,218 over 10 years, a gain of $84,218. See current MYGA rates.
Get your Allianz 222+ illustration for your age and state
Send us your premium amount, your state, and when you need the money. We will come back with current numbers on this contract and comparable ones from the 90+ top annuity companies on our platform, in writing.
Allianz 222+ Strengths and Red Flags
What it does well
- No rider fee: the income value, AIM benefit and Income Flex Benefit cost nothing extra, so no charge eats the account value.
- Rising income: the 150% interest bonus grows the income value before payments, then raises the check after.
- Strong carrier: AM Best A+, S&P AA and Moody’s Aa3, with Index Lock to lock a gain mid-term.
Red flags
- Low guaranteed income: $7,975 a year at 70, less than half the $16,875 Athene guaranteed on the same day.
- No guaranteed roll-up: a 0% year adds nothing to the income value.
- Backtest-heavy index: Morgan Stanley Strategic Trends 10 has 2 years of live history, yet shows the menu’s highest backtest, 13.35% on the 5-year term.
- 87.5% floor: the guaranteed cash value stays below premium until year 8.
- Long wait: 10-year surrender starting at 9.3%, and lifetime income can’t start until year 11.
Allianz 222+ vs Athene Ascent Pro 10 Bonus
| Feature | Allianz 222+ | Athene Ascent Pro 10 Bonus |
|---|---|---|
| Rider fee | None | 1% a year |
| Guaranteed income at 70 | $7,975 | $16,875 |
| Income after it starts | Rises with index credits | Level (Level Income option) |
| Surrender period | 10 years | 10 years |
Same-day illustrations, October 14, 2026: male, 60, Arizona, $100,000, income at 70. Athene guarantees more than twice the income; Allianz bets on index credits to close the gap.
Final verdict: the Allianz 222+ is built for income that can grow with the market. It earns our 3.5 rating for buyers who can wait 10 years. For more guaranteed income than the Allianz 222+ offers, consider the Athene Ascent Pro 10 Bonus; for safe growth, the Allianz Accumulation Advantage+.
Compare live rates on 137 fixed index annuities or visit our annuity review database.
Other Allianz Reviews
Also based on: Allianz and Athene illustrations via Annuities Genius, October 14, 2026.
This review is for educational purposes only and is not a recommendation or an offer to sell any annuity. Product features, index options, and rates can and do vary by state, and this product is not available for sale in every state. Always request a carrier illustration and work with a licensed annuity agent before you buy.
Frequently Asked Questions
How much income does the Allianz 222 pay on $100,000?
About $7,975 a year for life, guaranteed, starting at 70 for a man who buys at 60. With index credits, the hypothetical income was $25,872, but that is not guaranteed.
What is the difference between the Allianz 222 and the 222+?
The 222+ is the version Allianz sells today; it launched in May 2025. Anyone buying the Allianz 222 now gets the 222+.
Does the Allianz 222 have a rider fee?
No. The income value, AIM benefit and Income Flex Benefit are included. Some strategies carry an allocation charge, 0% today with a 2.5% maximum.
Is Allianz a good annuity company?
Allianz Life is rated A+ by AM Best, AA by S&P and Aa3 by Moody's. See our Allianz company review.



