
Is Allianz Benefit Control Annuity Good?
After completing my Allianz Benefit Control Annuity review, I don’t see a realistic client profile where Allianz Benefit Control (ABC) is the best annuity choice. Strong carrier, but this contract combines limited growth, high complexity, and underwhelming value. Below, I’ll quickly cover the features, what the illustration really shows, and where better options exist.
Based on the illustration and recent crediting history, its guaranteed values, surrender economics, and actual (not just hypothetical) performance don’t compete with simpler, higher‑yield alternatives or more transparent indexed designs.
While Allianz is a strong carrier, this specific contract asks the buyer to accept too little growth potential, too much complexity, and not enough value for the trade-offs. In short, I don’t see a client profile where this annuity would rise to the top of the shortlist. I’ll outline the features briefly and explain why.
Allianz Benefit Control at a Glance
| Detail | Information |
|---|---|
| Product Type | Fixed Index Annuity with Protected Income Value (PIV) rider |
| Issuing Carrier | Allianz Life Insurance Company of North America |
| AM Best / S&P / Comdex | A+ (Superior) / AA[3] / 93 |
| Surrender Period | 10 years |
| Surrender Schedule[2] | 9.3% / 9.3% / 8.3% / 7.3% / 6.25% / 5.25% / 4.2% / 3.15% / 2.1% / 1.05% |
| Minimum Premium | $20,000 |
| Income Base Bonus (PIV) | 25% on premium in the first 18 months |
| Current S&P 500 Cap | 4.00% (1-year point-to-point) |
| Allocation Charge | 0% current on most strategies; 0.95% on annual point-to-point indexed strategies; 2.5% maximum |
| Free Withdrawals | 10% of premium per year |
| Market Value Adjustment | Yes, on surrenders and excess withdrawals during the surrender period |
| Income Rider Fee | None (PIV rider bundled with the contract) |
How Much Income Does the Allianz Benefit Control Pay?
| Income feature | Accelerated PIV | Balanced PIV |
|---|---|---|
| Premium bonus to the PIV | 25% on premium in the first 18 months | 25% on premium in the first 18 months |
| Interest bonus to the PIV | 250% of credited interest | 150% of credited interest |
| Interest to your accumulation value | 50% of credited interest | Full credited interest |
| Income start | Age 50 or older, any monthly anniversary | Age 50 or older, any monthly anniversary |
| Income after it starts | Can rise in years interest is credited | Can rise in years interest is credited |
- Pick the right version: Accelerated fits buyers sure to take income; Balanced fits buyers who may never use it.
- The PIV is not cash: it sets your income, while surrenders pay from the smaller accumulation value.
- Income Multiplier: income can double with a qualifying confinement or 2 of 6 daily-living limits, after waiting periods.
- Compare the payout: run your age in our income rider calculator or the live quote below.
How Much Guaranteed Lifetime Income Can You Buy?
Live quotes from today’s carrier feedHypothetical Historical Rate of Return
The illustration we reviewed split $100,000 evenly across four strategies for a 74-year-old in Indiana.
| Strategy (25% each) | Current rate | 10-year annualized |
|---|---|---|
| S&P 500 1-year point-to-point | 4.00% cap | Capped at 4% in any year |
| Morgan Stanley Strategic Trends 10 ER | 45% participation | 4.74% |
| Bloomberg US Dynamic Balance III ER | 75% participation | 3.84% |
| PIMCO Tactical Balanced ER | 70% participation | Not illustrated |
| Blended illustration | – | 3.83% (about $145,700 after 10 years) |
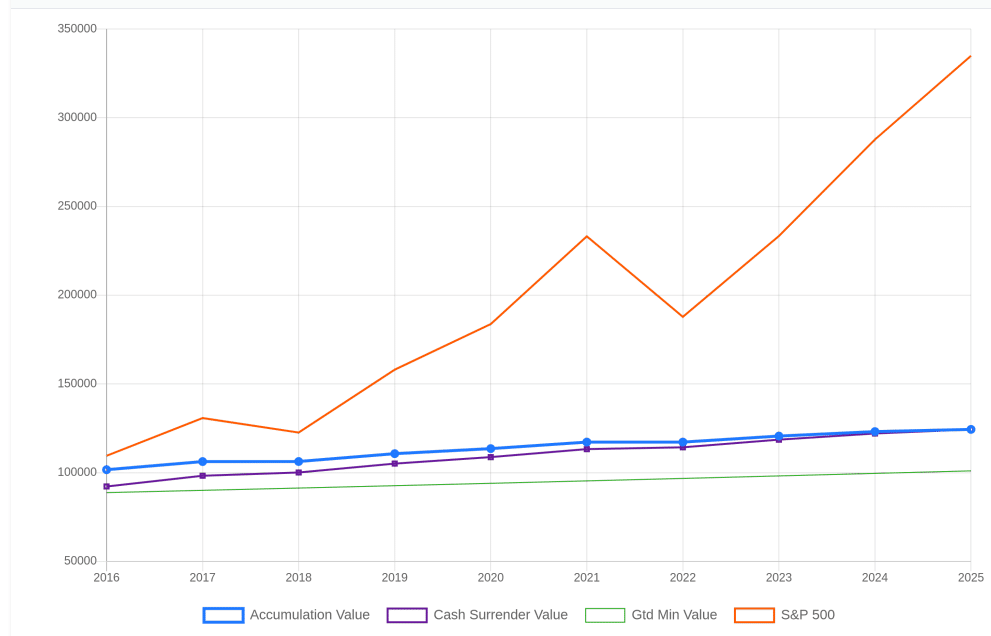
- The 4% cap is the problem: in a year the S&P 500 gains 25%, this contract credits 4%.
- Actual crediting lagged badly: on $100,000, the S&P 500 gained about $140,000 over 10 years; this contract about $24,000.
- Backtest caveat: these replay past years at today’s rates. Compare current fixed index annuity rates.
- MYGA benchmark: At today's top 10-year rate of 6.30% (compound), $100,000 grows to about $184,218 over 10 years, a gain of $84,218. See current MYGA rates.
Get your Allianz Benefit Control illustration for your age and state
Send us your premium amount, your state, and when you need the money. We will come back with current numbers on this contract and comparable ones from the 90+ top annuity companies on our platform, in writing.
Allianz Benefit Control Strengths and Red Flags
What it does well
- Income Multiplier: income can double for qualifying care needs.
- Index Lock: lock a positive index value any time during the crediting period.
- Rising income: payments can still increase after lifetime income starts.
Red flags
- 4% S&P 500 cap: well below what a guaranteed MYGA pays today.
- Accelerated PIV trade-off: only 50% of credited interest reaches your account value.
- Allocation charge: 0.95% on annual point-to-point strategies, up to a 2.5% maximum.
- 10-year lock-up: 9.3% charges in years 1 and 2, plus an MVA.
- Complexity: two income versions, an interest bonus and a separate PIV are hard to compare.
Final verdict: the Allianz Benefit Control is built for lifetime income, but its numbers trail simpler choices. It earns our 2.5 rating. For income, compare the Nationwide Peak 10; for safe growth, the Athene Performance Elite 7 beats the Allianz Benefit Control.
Compare live rates on 137 fixed index annuities or visit our annuity review database.
This review is for educational purposes only and is not a recommendation or an offer to sell any annuity. Product features, index options, and rates can and do vary by state, and this product is not available for sale in every state. Always request a carrier illustration and work with a licensed annuity agent before you buy.
Frequently Asked Questions
Is Allianz Benefit Control (ABC) a good annuity?
It’s a credible product from a strong insurer, but based on recent illustrations and guaranteed values, ABC rarely offers the best combination of growth potential, simplicity, and liquidity compared to alternatives like MYGAs or cleaner FIAs.
What are the main trade‑offs with ABC?
Complex crediting, modest caps/participation, and rider mechanics that add moving parts. You’re trading simplicity and competitive yield for a bundle of features that often underdeliver versus straightforward options.
How has ABC credited interest versus the S&P 500?
Illustrations show ABC credits lagging far behind the index due to caps, spreads, and volatility‑controlled designs. The gap is expected–FIAs don’t own equities–and ABC’s configuration amplifies that drag.
What do the guaranteed values and cash surrender values tell me?
They highlight limited downside but also limited upside and constrained access. If guaranteed value and liquidity are your priority, a MYGA or higher free‑withdrawal structure is usually cleaner.
Who, if anyone, should consider ABC?
Possibly someone who prioritizes a specific rider feature and accepts lower growth and extra complexity. For most buyers seeking yield, simple guarantees, or transparent indexing, better fits exist.
What alternatives usually beat ABC?
Multi‑Year Guaranteed Annuities (MYGAs) for fixed, high, simple yields; and select FIAs with competitive caps/participation and fewer moving parts. Product selection depends on age, state, horizon, and liquidity needs.
Are there big fees or surrender charges?
Like most deferred annuities, ABC includes surrender charges during the term and possible rider costs. Liquidity is typically limited to penalty‑free withdrawals; read the schedule before buying.



