What Is the Athene Performance Elite 10 Plus?
The Athene Performance Elite 10 Plus is the Athene Performance Elite 10 fixed index annuity with a Liquidity Rider attached for 0.95% a year. The rider adds a larger premium bonus (23% vs 20% on our illustrations), 10% free withdrawals from year 1, a return of premium guarantee after year 4, and penalty-free annuitization after year 7 (see the official Athene Performance Elite brochure).
This review compares matched live illustrations we ran on October 9, 2026 for a 60-year-old male with a $100,000 non-qualified premium, on both the Plus and the base Performance Elite 10.
Product Overview
| Feature | Details |
|---|---|
| Carrier | Athene Annuity and Life Company (AM Best A+, S&P A+, Fitch A+, Moody’s A1) |
| Product Type | Fixed Index Annuity (FIA), single premium, bonus |
| Liquidity Rider Charge | 0.95% of accumulated value per year for the 10-year withdrawal charge period; cannot be dropped during that period |
| Premium Bonus | 23% on our illustration (Enhanced Premium Bonus; varies by state and issue age). Vests 10% a year, fully vested after year 10 |
| Surrender Schedule | 8.3% / 8% / 7.1% / 6.2% / 5.3% / 4.4% / 3.5% / 2.6% / 1.6% / 0.9%, then 0% (varies by state), plus an MVA |
| Free Withdrawal | 10% per year from year 1; up to 20% if nothing was withdrawn the prior year |
| Return of Premium | After year 4, cash surrender value never falls below premium (less prior withdrawals) |
| Enhanced Annuitization | After year 7, annuitize the full accumulated value with no surrender charge, bonus forfeiture, or MVA |
| Death Benefit | Greatest of accumulated value, Minimum Guaranteed Contract Value, or the Return of Premium amount |
| Waivers | Confinement (60+ days, after year 1) and terminal illness (after year 1): up to 100% with no surrender charge or MVA |
| Premium / Issue Ages | $10,000 minimum ($5,000 in some states), $2,000,000 maximum / 0 to 78 |
| Income Rider | None |
Crediting Rates
On our illustrations, the Plus carried the same crediting rates as the base Performance Elite 10: 77% participation on the 1-year Nasdaq FC strategy and 130% on the 1-year BNP Paribas Multi-Asset Diversified 5 strategy. The full index menu and current rates are in our Performance Elite 10 review.
- The rider charge is deducted from accumulated value every year, so it reduces growth even in years when the index credits are strong.
- The Plus’s extra 3% bonus does not change the crediting rates; it only adds to the starting value.
- Compare current fixed index annuity rates across carriers on our FIA rate table.
Hypothetical Historical Rate of Return
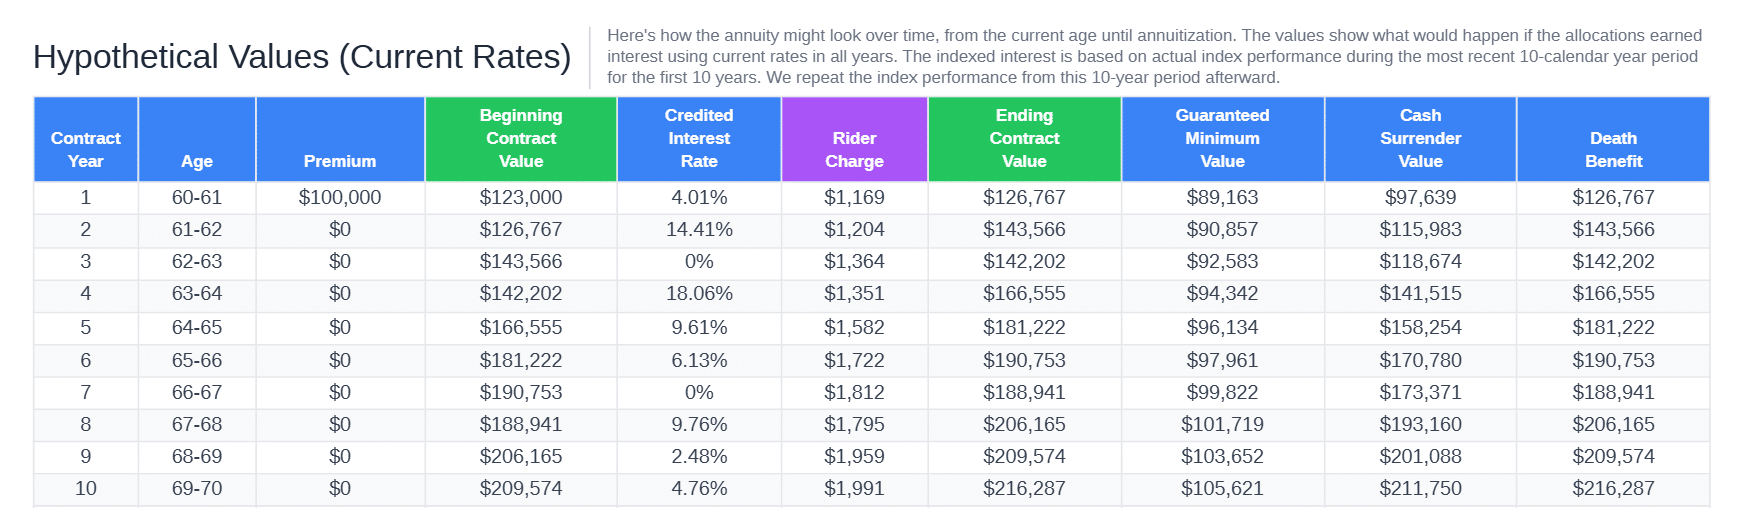
Illustration: $100,000 plus the 23% bonus ($123,000 accumulated value), 50% 1-year Nasdaq FC (77%) and 50% 1-year BNP Paribas (130%), no strategy fee, today’s rates applied to 2016 through 2025, with the 0.95% rider charge deducted.
| Year | 10 Plus Cash Value | Base 10 Cash Value | Difference |
|---|---|---|---|
| 1 | $97,639 | $95,380 | Plus +$2,259 |
| 7 | $173,371 | $178,335 | Base +$4,964 |
| 10 | $211,750 | $225,461 | Base +$13,711 |
- Total rider charges over 10 years: $15,949 in this illustration, against $3,000 of extra bonus.
- Annualized cash value: about 7.8% over 10 years for the Plus vs 8.5% for the base 10.
- Backtest caveat: Nasdaq FC did not exist before 2020, so four of these 10 years are simulated for that half of the allocation.
- MYGA benchmark: At today's top 10-year rate of 6.35% (compound), $100,000 grows to about $185,087 over 10 years, a gain of $85,087. See current MYGA rates.
Guaranteed Values (If the Index Pays 0% Every Year)
| Zero-Credit Scenario | 10 Plus | Base 10 |
|---|---|---|
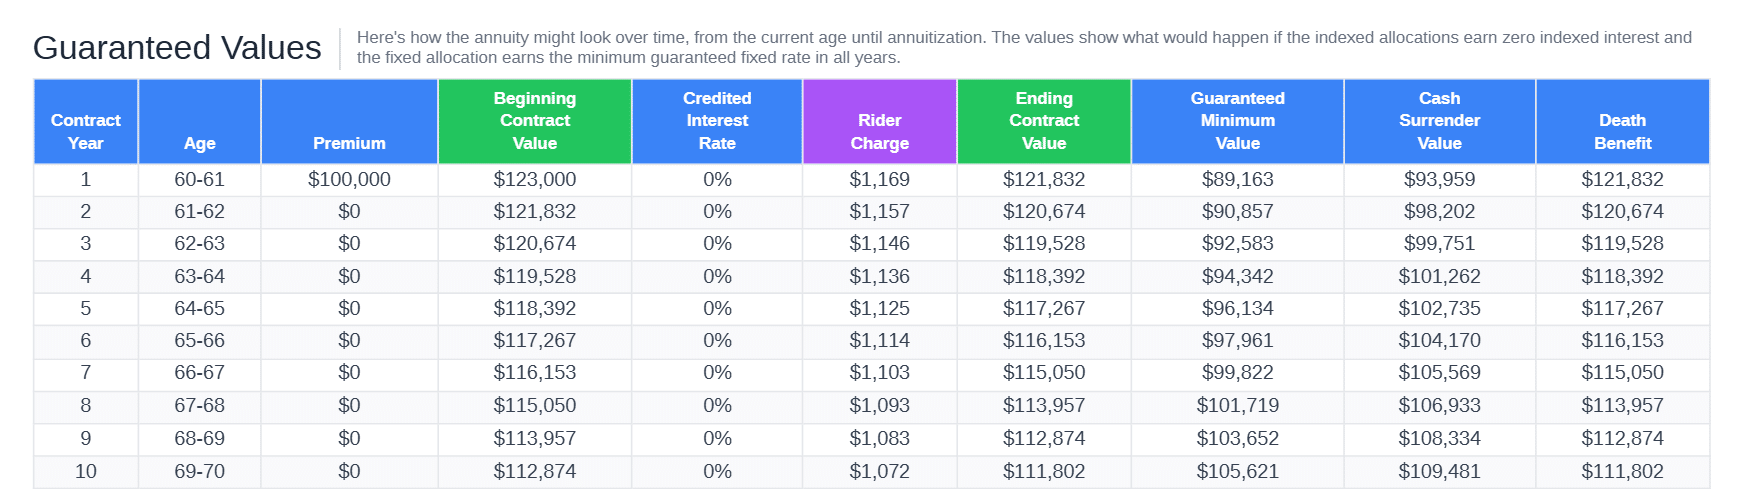
| Cash surrender value, year 1 | $93,959 | $91,700 |
| Cash surrender value, year 4 | $101,262 | $100,810 |
| Cash surrender value, year 10 | $109,481 | $117,245 |
| Accumulated value / death benefit, year 10 | $111,802 | $120,000 |
| Total rider charges | $11,198 | $0 |
- With no index credits, the rider charge shrinks the accumulated value from $123,000 to $111,802 by year 10.
- The Plus is ahead through year 4 and behind from year 5 on.
- Return of Premium matters most as protection against a negative MVA on an early surrender after year 4; in this illustration the base 10’s cash value already passed premium in year 4.
Performance Elite 10 Plus vs Performance Elite 10
| 10 Plus | Base 10 | |
|---|---|---|
| Annual rider charge | 0.95% | None |
| Premium bonus (our illustrations) | 23% | 20% |
| Free withdrawal | 10% from year 1 (20% after a year with none) | 5% from year 2 |
| Return of premium | After year 4 | No |
| Penalty-free annuitization | After year 7 | No |
| Illustrated cash value, year 10 | $211,750 | $225,461 |
| Guaranteed cash value, year 10 | $109,481 | $117,245 |
In short, the rider charges more than it gives back unless you actually use the extra liquidity. For buyers whose main concern is liquidity, the no-bonus Athene Performance Elite 7 offers 10% free withdrawals from year 1 with no rider charge and a 7-year surrender period.
Pros and Cons
Pros
- Larger premium bonus (23% vs 20% on our illustrations)
- 10% free withdrawals from year 1, up to 20% after a year with no withdrawal
- Return of Premium after year 4, including protection from a negative MVA
- Penalty-free annuitization after year 7, three years before the surrender period ends
- Strong carrier backing. Athene holds an A+ rating from AM Best
Cons
- 0.95% annual rider charge for 10 years: $15,949 in our hypothetical, $11,198 even with zero credits
- Lower values than the base 10 from year 5 on, in both the hypothetical and guaranteed scenarios
- Same compressed crediting rates as the base 10 (about 59% of the Performance Elite 7’s)
- 10-year surrender period plus an MVA
- No lifetime income rider
Bottom Line Verdict
Best for a buyer who wants a bonus FIA and expects to take more than 5% a year, or who values the return-of-premium floor and the option to annuitize penalty-free after year 7. Otherwise, the base Performance Elite 10 comes out ahead, and the Performance Elite 7 gives 10% liquidity with no rider charge. Request matched illustrations for your age and state.
Frequently Asked Questions
What does the Athene Performance Elite 10 Plus rider cost?
0.95% of accumulated value per year during the 10-year withdrawal charge period. It cannot be dropped during that period. In our $100,000 illustration it totaled $15,949 over 10 years.
What is the Performance Elite 10 Plus premium bonus?
23% on our illustration, versus 20% on the base Performance Elite 10. The bonus varies by state and issue age, vests 10% a year, and is fully vested after year 10.
How much can I withdraw penalty-free from the Performance Elite 10 Plus?
Up to 10% of accumulated value per year starting in year 1, or up to 20% if you took no withdrawal the prior year. RMDs count toward the free amount.
What is the Return of Premium Benefit?
After the fourth contract year, your cash surrender value will never be less than your premium minus prior withdrawals, even after surrender charges, bonus forfeiture, and a negative MVA.
Is the Performance Elite 10 Plus better than the base Performance Elite 10?
Only if you use the extra liquidity. On our matched illustrations, the base 10 had $13,711 more cash value at year 10, and $7,764 more in the zero-credit scenario.
Does the Performance Elite 10 Plus have an income rider?
No. The Liquidity Rider is not an income rider. Athene products like the Athene Agility 10 pair better with income riders.
Other Athene Reviews
Sources: Athene Performance Elite brochure (04/22/26); Athene illustrations via Annuities Genius, October 9, 2026; NAIC Consumer Information Source.
This review is for educational purposes only and is not a recommendation or an offer to sell any annuity. Product features, index options, and rates can and do vary by state, and this product is not available for sale in every state. Always request a carrier illustration and work with a licensed annuity agent before you buy.