What Is the Athene Performance Elite 7 Plus?
The Athene Performance Elite 7 Plus is the Athene Performance Elite 7 fixed index annuity with a Liquidity Rider attached for 0.95% a year. The rider adds a 5% premium bonus on our illustration, up to 20% free withdrawals after a year with none, a return of premium guarantee after year 4, and penalty-free annuitization after year 5. Crediting rates are identical to the base Performance Elite 7 (see the official Athene Performance Elite brochure).
This review compares matched live illustrations we ran on October 9, 2026 for a 60-year-old male with a $100,000 non-qualified premium, on both the 7 Plus and the base Performance Elite 7.
Product Overview
| Feature | Details |
|---|---|
| Carrier | Athene Annuity and Life Company (AM Best A+, S&P A+, Fitch A+, Moody’s A1) |
| Product Type | Fixed Index Annuity (FIA), single premium, bonus |
| Liquidity Rider Charge | 0.95% of accumulated value per year for the 7-year withdrawal charge period; cannot be dropped during that period |
| Premium Bonus | 5% on our illustration (varies by state). Vests 0% / 5% / 15% / 25% / 40% / 60% / 80%, fully vested after year 7 |
| Surrender Schedule | 9% / 8.8% / 7.9% / 6.9% / 5.9% / 5% / 4%, then 0%, plus an MVA |
| Free Withdrawal | 10% per year from year 1; up to 20% if nothing was withdrawn the prior year |
| Return of Premium | After year 4, cash surrender value never falls below premium (less prior withdrawals) |
| Enhanced Annuitization | After year 5, annuitize the full accumulated value with no surrender charge, bonus forfeiture, or MVA |
| Death Benefit | Greatest of accumulated value, Minimum Guaranteed Contract Value, or the Return of Premium amount |
| Waivers | Confinement (60+ days, after year 1) and terminal illness (after year 1): up to 100% with no surrender charge or MVA |
| Premium / Issue Ages | $10,000 minimum, $2,000,000 maximum / 0 to 83 |
| Income Rider | None |
Crediting Rates
Athene’s October 9, 2026 rate sheet for the 7 Plus matches the base Performance Elite 7 line for line, including the 4.85% fixed account. Highlights with no strategy fee:
- 1-year Nasdaq FC: 130% participation
- 1-year BNP Paribas Multi-Asset Diversified 5: 220% participation
- 1-year S&P 500: 9.75% cap
- 1-year fixed account: 4.85%
The full index menu, fee-based rates, and backtests are in our Performance Elite 7 review. You can also compare current fixed index annuity rates across carriers.
Hypothetical Historical Rate of Return
Illustration: $100,000 plus the 5% bonus ($105,000 accumulated value), 50% 1-year Nasdaq FC (130%) and 50% 1-year BNP Paribas (220%), no strategy fee, today’s rates applied to 2016 through 2025, with the 0.95% rider charge deducted.
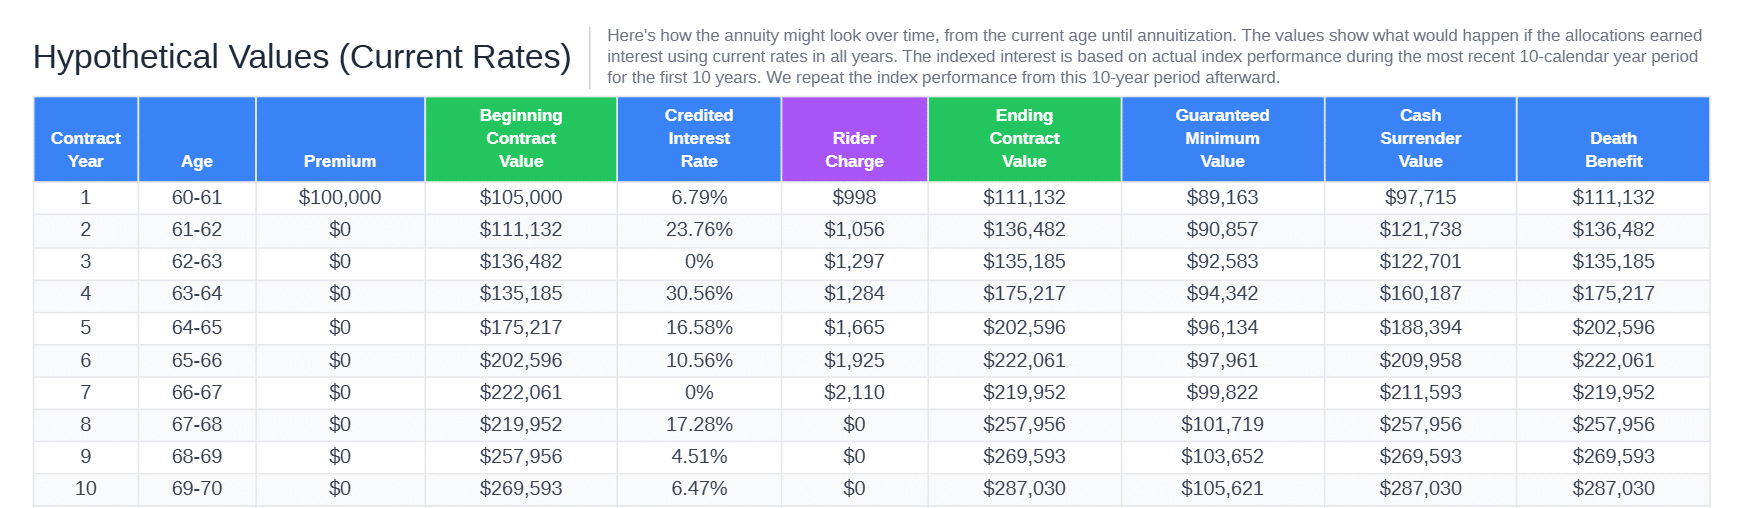
| Year | 7 Plus Cash Value | Base 7 Cash Value | Difference |
|---|---|---|---|
| 1 | $97,715 | $98,079 | Base +$364 |
| 7 | $211,593 | $214,391 | Base +$2,798 |
| 10 | $287,030 | $290,221 | Base +$3,191 |
- Total rider charges over 7 years: $10,335 in this illustration, against a $5,000 bonus.
- The rider stops after year 7, so the gap stays roughly flat after the surrender period ends.
- Annualized cash value at year 7: about 11.3% for the 7 Plus vs 12.1% for the base 7.
- Backtest caveat: Nasdaq FC did not exist before 2020, so four of these 10 years are simulated for that half. We would plan around 4% to 7% a year, not the illustrated figures.
- MYGA benchmark: At today's top 7-year rate of 7.10% (simple interest), $100,000 grows to about $149,700 over 7 years, a gain of $49,700. See current 7-year MYGA rates.
Guaranteed Values (If the Index Pays 0% Every Year)
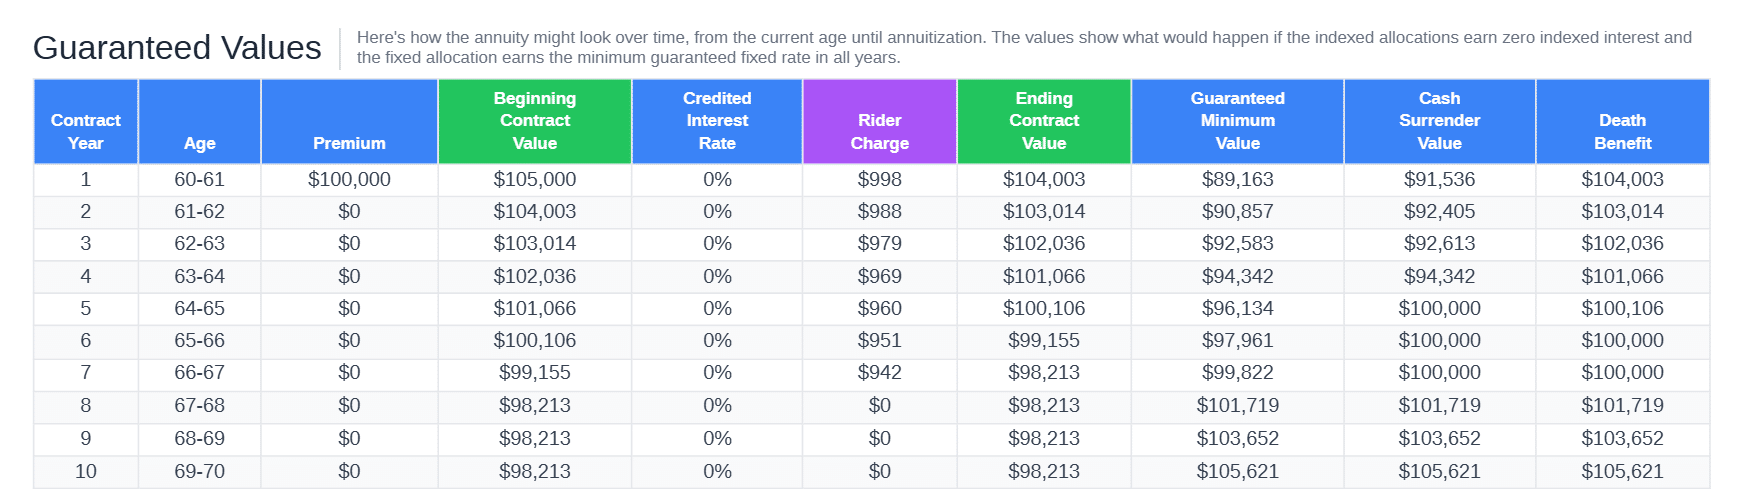
| Zero-Credit Scenario | 7 Plus | Base 7 |
|---|---|---|
| Cash surrender value, year 1 | $91,536 | $91,900 |
| Cash surrender value, year 5 | $100,000 | $96,134 |
| Cash surrender value, year 7 | $100,000 | $99,822 |
| Cash surrender value, year 10 | $105,621 | $105,621 |
| Total rider charges | $6,787 | $0 |
- Return of Premium is the 7 Plus’s real advantage. From year 5 on, the cash value can’t fall below $100,000, even after surrender charges and a negative MVA. In the zero-credit scenario that puts it $3,866 ahead of the base 7 in year 5.
- The rider charges shrink accumulated value to $98,213 by year 7, but the Return of Premium floor holds the cash value at $100,000.
- After year 7 both versions land on the same guaranteed minimum ($105,621 in year 10).
Performance Elite 7 Plus vs Performance Elite 7
| 7 Plus | Base 7 | |
|---|---|---|
| Annual rider charge | 0.95% for 7 years | None |
| Premium bonus (our illustrations) | 5% | None |
| Crediting rates | Identical | Identical |
| Free withdrawal | 10% from year 1 (20% after a year with none) | 10% from year 1 |
| Return of premium | After year 4 | No |
| Penalty-free annuitization | After year 5 | No |
| Illustrated cash value, year 7 | $211,593 | $214,391 |
| Guaranteed cash value, year 5 | $100,000 | $96,134 |
The 7 Plus costs about $2,800 by year 7 in a strong market and protects about $3,900 in a flat one. That is a much smaller trade-off than the Performance Elite 10 Plus, where the same rider cost $13,711 by year 10.
Pros and Cons
Pros
- Return of Premium after year 4: cash value never below premium, even with a negative MVA
- Same crediting rates as the base 7, including 130% Nasdaq FC, 220% BNP Paribas, and the 4.85% fixed account
- 5% premium bonus offsets about half the rider charges
- Up to 20% free withdrawals after a year with none, and penalty-free annuitization after year 5
- Strong carrier backing. Athene holds an A+ rating from AM Best
Cons
- 0.95% annual rider charge for 7 years: $10,335 in our hypothetical
- Slightly lower values than the base 7 whenever the index performs well ($2,798 behind at year 7)
- Bonus vests slowly, only 40% by year 5
- 7-year surrender period plus an MVA
- No lifetime income rider
Bottom Line Verdict
Best for a cautious buyer who wants the Performance Elite 7’s rates but worries about surrendering early into a negative MVA or a flat market. If you’re confident you’ll hold all 7 years and only need 10% a year, the base Performance Elite 7 comes out slightly ahead. Request matched illustrations on both for your age and state.
Frequently Asked Questions
What does the Athene Performance Elite 7 Plus rider cost?
0.95% of accumulated value per year during the 7-year withdrawal charge period, and it can’t be dropped during that period. In our $100,000 illustration it totaled $10,335.
What is the Performance Elite 7 Plus premium bonus?
5% on our illustration (it varies by state). It vests 0%, 5%, 15%, 25%, 40%, 60%, and 80% over years 1 through 7 and is fully vested after year 7. The base Performance Elite 7 has no bonus.
Are the Performance Elite 7 Plus rates different from the Performance Elite 7?
No. On Athene’s October 9, 2026 rate sheet, every crediting rate and the 4.85% fixed account are identical on both versions.
What is the Return of Premium Benefit?
After the fourth contract year, your cash surrender value will never be less than your premium minus prior withdrawals, even after surrender charges, bonus forfeiture, and a negative MVA.
Is the Performance Elite 7 Plus better than the base Performance Elite 7?
It depends on whether you value protection over upside. On our matched illustrations, the base 7 had $2,798 more cash value at year 7 in a strong market, while the 7 Plus had $3,866 more in year 5 if the index paid nothing.
Does the Performance Elite 7 Plus have an income rider?
No. The Liquidity Rider is not an income rider. Athene products like the Athene Agility 10 pair better with income riders.
Other Athene Reviews
Sources: Athene Performance Elite brochure (04/22/26); Athene rate sheets and illustrations via Annuities Genius, October 9, 2026; NAIC Consumer Information Source.
This review is for educational purposes only and is not a recommendation or an offer to sell any annuity. Product features, index options, and rates can and do vary by state, and this product is not available for sale in every state. Always request a carrier illustration and work with a licensed annuity agent before you buy.